A home appraisal in NJ gives you an independent, written opinion of what a property is worth. Picture this: your offer is accepted and the inspection goes well, but then the appraisal comes in below the price you agreed to pay. Knowing what appraisers look at, and what to do with a low number, keeps that moment from derailing your plans. This guide walks you through the process from the visit to the final report.
Key takeaways
An appraisal is an independent opinion of value, usually ordered for your lender.
Appraisers weigh size, condition, updates, location and recent nearby sales.
For a typical first mortgage, you get a copy no later than three days before closing.
A low value is a reason to check for errors, renegotiate or rethink the deal.
What a Home Appraisal in NJ Is, and What It Is Not
The Consumer Financial Protection Bureau describes an appraisal as a written document that shows an opinion of how much a property is worth. It also calls the appraisal an independent assessment of value. In other words, the appraiser does not work to please the buyer or the seller. The report describes what makes the home valuable, and it may show how the home compares with others nearby.
People often mix up appraisals and inspections. However, each one answers a different question:
Appraisal
Home inspection
Main question
What is the home worth?
What condition is it in?
Usually arranged by
The lender
The buyer
What you get
A written opinion of value
A report on systems and defects
The state’s home buying guide strongly recommends an independent home inspection soon after your contract becomes binding. So plan on both if you are buying with a loan.
Why Lenders Order a Home Appraisal
When you borrow money to buy or refinance, your lender may need a new appraisal. That is because the home secures the loan, so the lender wants to know its value. The lender may also ask you to pay for it, and it may use other ways to check the value as well.
You have rights here, too. For a typical first mortgage, the CFPB says you are entitled to a copy of the appraisals and other valuations your lender gets. You should receive them soon after they are complete, and no later than three days before closing. The lender cannot charge you for the copies themselves. However, it can charge a reasonable fee for the cost of the appraisal.
Clear rooms and easy access to the basement, attic and mechanicals help the visit go smoothly.
What Appraisers Look At
An appraiser visits the home, takes notes and photos, and then studies the local market. Here are common factors they review:
Location, including the street, the town and nearby features
Size, layout and the number of bedrooms and bathrooms
Age and overall condition of the house
Updates, such as a newer kitchen, roof or heating system
The lot, plus extras like a garage, deck or finished basement
Recent sales of similar homes and current market trends
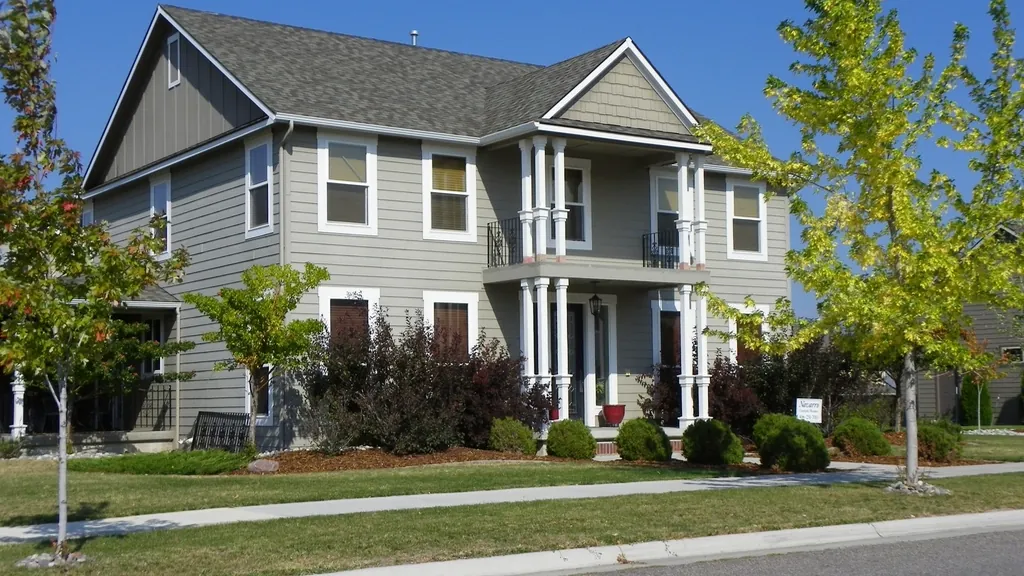
The appraiser looks at the home as it is on the day of the visit. So a project you plan to finish next year will not count yet.
How Comparable Sales Shape the Value
Comparable sales, or “comps,” are recent sales of similar homes nearby. They carry a lot of weight because they show what real buyers paid. The appraiser picks the closest matches, then adjusts for differences. For example, a comp with an extra bathroom may get a downward adjustment, while a comp with a smaller yard may get an upward one.
That is why two homes on the same street can appraise for different amounts. Condition, size and updates all move the final number. Market timing matters too, since prices can shift from one season to the next.
How to Prepare for a Home Appraisal in NJ
You cannot control the market during a home appraisal in NJ, but you can make the visit go smoothly. Start by tidying up so the appraiser can see each room clearly. Then work through these steps:
Fix small issues. Repair things like a loose railing, a leaky faucet or a missing outlet cover.
List your updates. Note each project with its date and, if you have it, the rough cost.
Gather paperwork. Pull together permits, surveys and warranties for major work.
Clear the way. Make sure the appraiser can reach the attic, basement, furnace and water heater.
Secure pets. That way, the appraiser can move around safely and quickly.
Share what a visitor might miss. Point out features that are easy to overlook, such as a new sewer line.
If you are the seller, these steps help you as well. In many sales, the buyer’s lender orders the appraisal, but the visit still happens in your home. Finally, let the appraiser do the job. The CFPB notes that appraisers must follow rules, and lenders may not interfere with their judgment.
Square footage drives value, so check the report’s measurements and room count for errors.
What to Do If Your Home Appraisal Comes In Low
A low home appraisal in NJ can feel like a setback. Even so, it gives you useful facts. The CFPB says it is very risky to buy a home for more than its appraised value, and it suggests a clear order of steps. First, get a copy of the appraisal and read it closely. Next, ask the seller to lower the price, since the appraisal is strong evidence of market value. If the seller will not budge, consider whether to cancel the sale.
Watch out: Your purchase contract shapes your options, and canceling may carry costs. The CFPB suggests you consult an attorney before you decide. Still, it notes that those costs are likely small compared with buying a home that is not worth what you paid.
Tip: Check the report for simple errors, such as the wrong square footage or room count. If you find one, tell your lender and ask how it handles questions about the report.
How to Check an Appraiser’s Credentials
States license and certify appraisers, and each state sets its own process. In New Jersey, the State Board of Real Estate Appraisers oversees appraiser licensing. At the federal level, the Appraisal Subcommittee keeps a national registry of appraisers. It also runs a national hotline that refers complaints about appraisal independence to the right state and federal agencies.
Home Appraisal in NJ: Questions Owners Ask
Who pays for a home appraisal?
When you take out a loan to buy or refinance, your lender may require you to pay for the appraisal. Ask about the cost early so it fits your budget, and look for it on your loan paperwork.
Can I get a copy of my appraisal?
Yes, for a typical first mortgage. The CFPB says your lender must send you a copy soon after it is complete, and no later than three days before closing. The lender cannot charge you for the copy itself.
Can my lender push the appraiser for a higher value?
No. The CFPB notes that appraisers have to follow rules in reaching a value, and lenders are not allowed to interfere with the appraiser’s judgment. If you think the process was not independent, the Appraisal Subcommittee’s hotline can point you to the right agency.
How Tom Conerford Can Help
Tom Conerford provides real estate appraisal services through TBT Appraisals LLC. TBT is a New Jersey company whose state registration lists Livingston, in Essex County. An appraisal gives homeowners, buyers, sellers and their advisors an independent opinion of a property’s market value.
This article is general information, not legal or financial advice. For advice about your own property or loan, speak with a licensed appraiser, your lender or a New Jersey real estate attorney.
 With Erika Baldino Title Insurance